Under IRS rules, mining rewards are generally taxable as ordinary income when received, while selling or swapping those rewards later can trigger capital gains or losses.
For home miners, taxes also depend on whether mining qualifies as a hobby or business. That distinction affects electricity deductions, hardware depreciation, self-employment tax and reporting requirements.
This guide explains how U.S. crypto mining taxes work in 2026, which expenses may be deductible, how to calculate taxable income and what records and IRS forms home miners need.
Editor's Note (Oct. 9, 2026): We fully updated this guide in October 2026 to reflect U.S. crypto mining tax rules in 2026. We expanded coverage of hobby vs. business classification, taxable mining rewards, electricity deductions, ASIC depreciation and capital gains. We also added practical tax calculations, mining-pool reporting, recordkeeping guidance, IRS forms and estimated tax requirements, alongside recent legislative developments and changes to digital-asset reporting.
Home Crypto Mining Taxes: Quick Answer
Crypto mining rewards are generally taxable as ordinary income when received, even if the coins are not sold. Their fair market value in U.S. dollars establishes the starting cost basis. Selling, swapping or spending the mined crypto later can trigger a separate capital gain or loss. Whether mining qualifies as a hobby or business determines which expenses may be deductible and whether self-employment tax applies.
How Home Crypto Mining Taxes Work
-
Mining rewards create taxable income when received The fair market value of crypto when the miner gains control is generally included in gross income, even if the coins remain unsold.
-
Selling mined crypto can trigger capital gains or losses The value reported as mining income generally becomes the starting cost basis. A later taxable disposal creates a gain or loss based on the difference between proceeds and adjusted basis.
-
Hobby and business miners follow different tax rules Both generally report mining income. Qualifying business miners may deduct ordinary and necessary expenses, while hobby miners generally cannot claim the same Schedule C deductions.
-
Business miners may deduct electricity and operating costs Eligible expenses can include mining electricity, pool fees, maintenance, software and the business portion of internet costs. Personal and business use must be separated and documented.
-
ASICs and mining hardware follow depreciation rules Qualifying business equipment may be eligible for Section 179 expensing, bonus depreciation or MACRS. The applicable treatment depends on eligibility, business use and when the equipment is placed in service.
-
The $400 threshold is not a mining income exemption The $400 rule generally relates to net earnings subject to self-employment tax. Business miners may owe self-employment tax, while mining income can remain taxable below that threshold.
-
Accurate records determine whether tax reporting holds up Track reward timestamps, USD values, pool payouts, wallet transfers, electricity, equipment costs and later disposals. Hobby income generally goes on Schedule 1, business income on Schedule C and capital-asset sales on Form 8949 and Schedule D where required.
Disclaimer
This guide is for educational purposes only and does not constitute tax, legal or financial advice. Tax treatment depends on individual circumstances, business classification, applicable elections and current legislation. State and local rules may differ. Consult a qualified tax professional before making tax-related decisions.
Disclosure
Some links in this guide may be affiliate links. If you choose to use a service through these links, we may earn a commission at no additional cost to you.

How Are Home Crypto Mining Rewards Taxed?
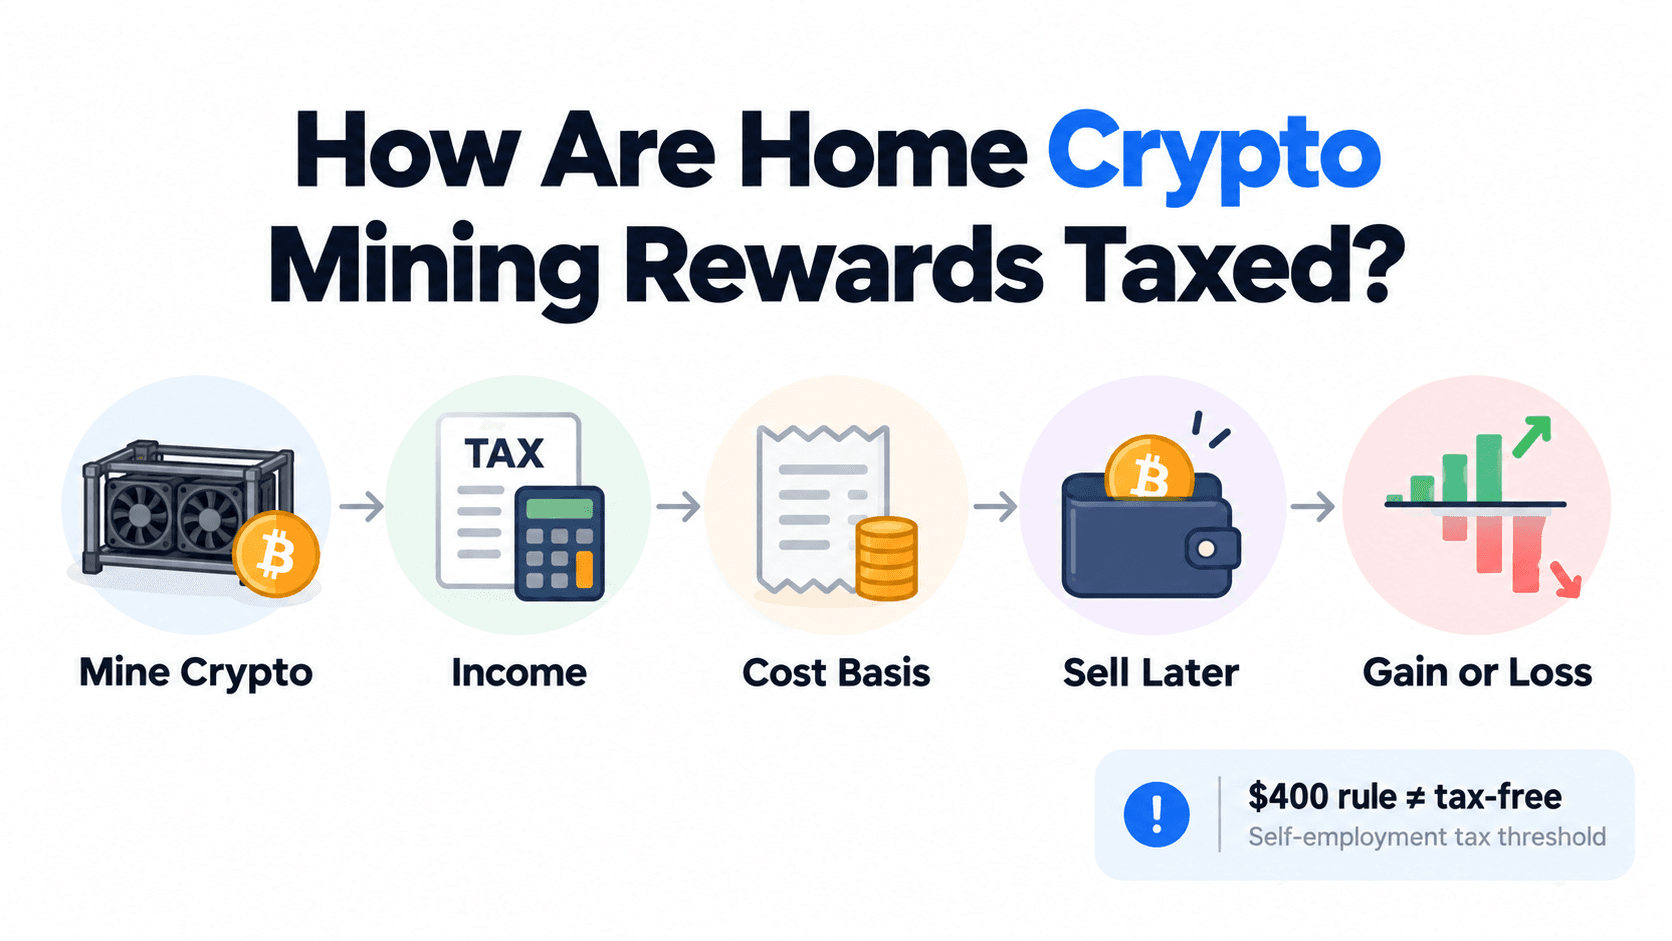
First comes ordinary income when the mining reward is received. Later, disposing of that crypto can create a capital gain or loss.
The sequence is:
Mine crypto → recognize income → establish cost basis → later dispose of crypto → calculate gain or loss.
For readers who need the mechanics behind block rewards, Coin Bureau's guide to Bitcoin mining explains how miners earn BTC by contributing computational power to the network.
 Mining Rewards Create Income Before Later Capital Gains
Mining Rewards Can Create Income When You Receive Them
IRS Notice 2014-21 established the core federal rule: when a taxpayer successfully mines virtual currency, its fair market value on the date of receipt is included in gross income. Keeping the coins instead of selling them immediately does not postpone that income recognition.
For digital assets, receipt generally turns on when the taxpayer has sufficient control over the asset. IRS guidance describes control in practical terms as being able to transfer, sell, exchange or otherwise dispose of the crypto. That becomes relevant when rewards remain inside a pool account before reaching an external wallet.
The income is measured in U.S. dollars. A miner who receives 0.01 BTC worth $1,000 when it becomes taxable generally records $1,000 of income even if the BTC stays untouched for months.
A missing tax form does not erase the transaction. The IRS requires taxpayers to report taxable digital-asset income, gains and losses whether or not an information return was received.
Selling Mined Crypto Can Create a Second Tax Event
The value included in income generally becomes the starting basis in the mined crypto. A later sale, exchange or other taxable disposal compares the disposal proceeds with that basis.
Suppose a miner receives BTC worth $1,000 and reports $1,000 of mining income. The miner's starting basis is $1,000. If the BTC is later sold for $1,300, the difference is a $300 capital gain.
If that same $1,000 mining reward later sells for $700, the miner still has the original $1,000 of income from mining, followed by a potential $300 capital loss on the later disposition.
The first calculation measures income created through mining. The second measures the gain or loss while the miner held the asset.
The $400 Rule Does Not Make Mining Income Tax-Free
The often-repeated “$400 crypto mining threshold” refers to self-employment tax, not a blanket federal income-tax exemption.
A self-employed person generally files Schedule SE when net earnings from self-employment reach $400 or more. Whether mining is actually a trade or business must first be determined from the facts. A hobby miner does not automatically become a business miner after crossing $400, and mining income below $400 does not automatically become tax-free.
Congress is also considering changes to digital-asset taxation in 2026. The House Ways and Means Committee approved the Digital Asset Tax Certainty Act, H.R. 10357, on September 16, 2026, including provisions affecting mining and staking rewards. As of Oct. 9, 2026, the proposal has not become law. Current federal tax rules therefore continue to apply unless legislation is enacted.
Is Your Crypto Mining a Hobby or a Business?
The IRS does not classify mining from a rig count, revenue threshold or number of hours worked. Classification depends on whether the activity is genuinely conducted for profit and operated in a businesslike manner.
Business treatment can bring Schedule C deductions and self-employment tax into the calculation. Hobby treatment follows a different reporting framework.
How the IRS Looks at Hobby vs. Business Activity
There is no rule saying three ASICs make a business while one ASIC makes a hobby. The IRS instead looks at the full set of facts and circumstances, and no single factor decides the outcome.
For a home miner, useful indicators include:
- Regularity and continuity: Running equipment consistently looks more businesslike than occasional experimentation.
- Records: Separate accounts, invoices, pool statements and electricity calculations support a commercial operation.
- Expertise: Knowledge of mining economics, hardware, energy pricing and operating costs can support a profit motive.
- Time and effort: Substantial ongoing work can point toward business activity.
- Profitability efforts: Changing pools, hardware, operating hours or energy arrangements to improve margins shows commercial intent.
- History of income and losses: Persistent losses do not automatically disqualify a business, but the reasons for those losses affect the analysis.
- Dependence on the income: Relying on mining revenue can support business treatment, although it is not required.
Schedule C instructions similarly describe a business as an activity conducted primarily for income or profit with continuity and regularity. Sporadic or not-for-profit activity generally does not qualify.
Hobby Mining vs. Business Mining
| Criteria | Hobby Miner | Business Miner |
|---|---|---|
| Mining rewards taxable | Yes | Yes |
| Schedule C | Generally no | Generally yes |
| Self-employment tax | Generally no | Potentially yes |
| Ordinary business expenses | Generally unavailable as business deductions | Potentially deductible |
| Hardware depreciation | Generally no business depreciation deduction | Potentially available |
| Estimated taxes | Depends on overall tax position | Commonly relevant |
Business classification determines whether the miner can move from reporting gross income to calculating business profit after allowable expenses. A hobby miner still reports mining income, but the Schedule C framework for ordinary and necessary business costs generally belongs to activities that qualify as a trade or business.
What Different Home Mining Setups Might Look Like
Consider three miners.
A casual miner runs a small machine occasionally, keeps limited records and makes no sustained attempt to optimize profitability. Those facts lean toward hobby treatment, although classification still depends on the complete picture.
A more organized operator runs several ASICs continuously, tracks power consumption separately, maintains expense records, compares pool economics and regularly adjusts the setup to improve profitability. Those facts provide stronger evidence of a trade or business.
A full-time employee with a mining operation can still have business mining income. Having W-2 wages elsewhere does not prevent someone from running a separate legitimate trade or business. It simply gives the taxpayer more than one source of income.
How to Calculate Taxable Income From Mining
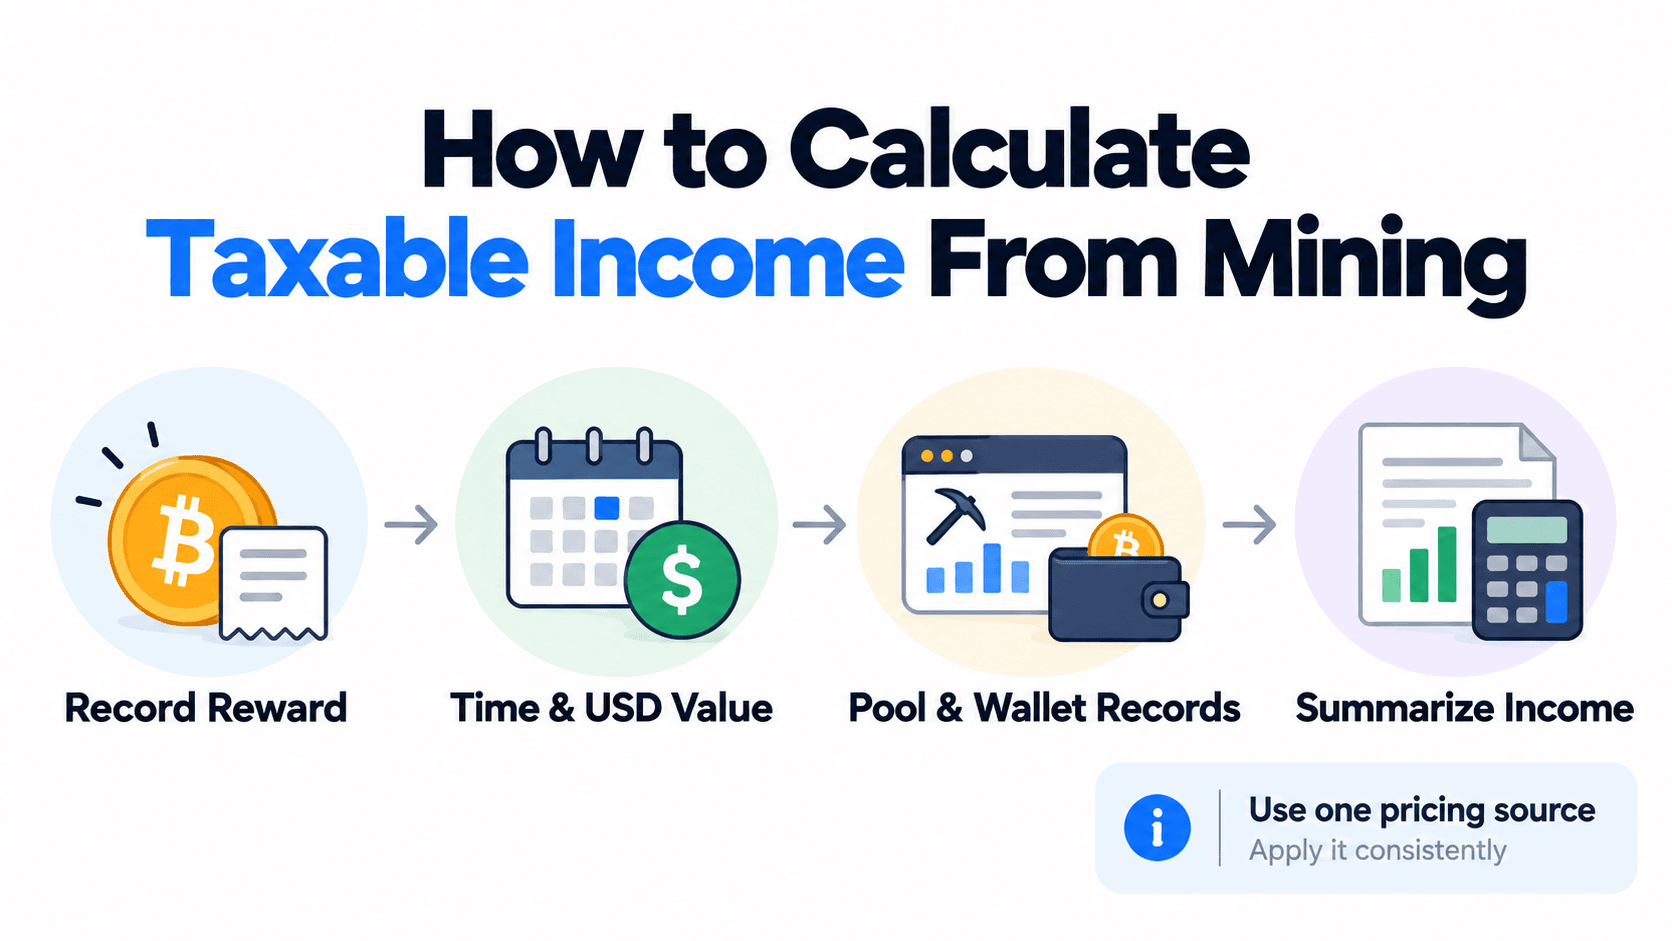
Calculating mining income requires more than counting coins at year-end. A defensible record connects each taxable reward with the quantity received, when the miner obtained control and its U.S. dollar value at that point.
A few payouts can be tracked manually. Hundreds or thousands of pool credits usually require exports and accounting software.
 Calculating Mining Income Starts With Accurate Reward Valuations
Determine the Fair Market Value of Each Mining Reward
For each reward, record:
- The crypto asset and quantity
- The date and time it became taxable
- Its fair market value in U.S. dollars
- The pricing source used
- The mining-pool or wallet account involved
IRS guidance allows exchange-listed virtual currency to be converted into U.S. dollars using an exchange rate determined in a reasonable manner that is consistently applied.
For rewards that can be matched to an exact transaction time, a contemporaneous exchange or reputable market-data value provides a clearer record than an unexplained daily estimate. The miner should document the methodology and apply it consistently rather than switching pricing sources according to which produces the lowest taxable value.
How Mining Pool Payouts Affect Tax Records
Mining pools complicate tax records because “earned,” “credited” and “paid to wallet” may occur at different times.
A pool may:
- Track rewards inside an internal account
- Apply a minimum payout threshold
- Deduct pool fees
- Pay to an external wallet only after the balance reaches a set amount
- Generate many small credits before producing one blockchain payout
No single pool event can be treated as the universal taxable moment for every arrangement. The analysis depends on when the miner obtains control of the reward under the specific pool terms and payout mechanics.
Keep both the pool-side history and wallet payout history. Where available, preserve gross reward amounts, fees, timestamps and payout records rather than relying only on the net amount that eventually arrives in a wallet.
Those two data sets let the miner reconcile a pool dashboard against an onchain payout without guessing months later where the difference came from.
Can You Combine Small Mining Rewards?
A miner may accumulate hundreds or thousands of small reward records. That does not mean every payment has to be manually typed onto a tax return.
Preserve transaction-level source data and use accounting or tax software to summarize it where the workflow permits. CSV exports, wallet histories and pool reports should remain available underneath the final tax report.
For high-volume records, Coin Bureau's comparison of crypto tax software covers transaction limits, reconciliation tools, wallet-by-wallet basis support and Form 1099-DA workflows.
Aggregation can simplify the final report. It does not replace the source records needed to explain how the summarized figures were calculated.
Which Home Crypto Mining Expenses Can Be Deducted?
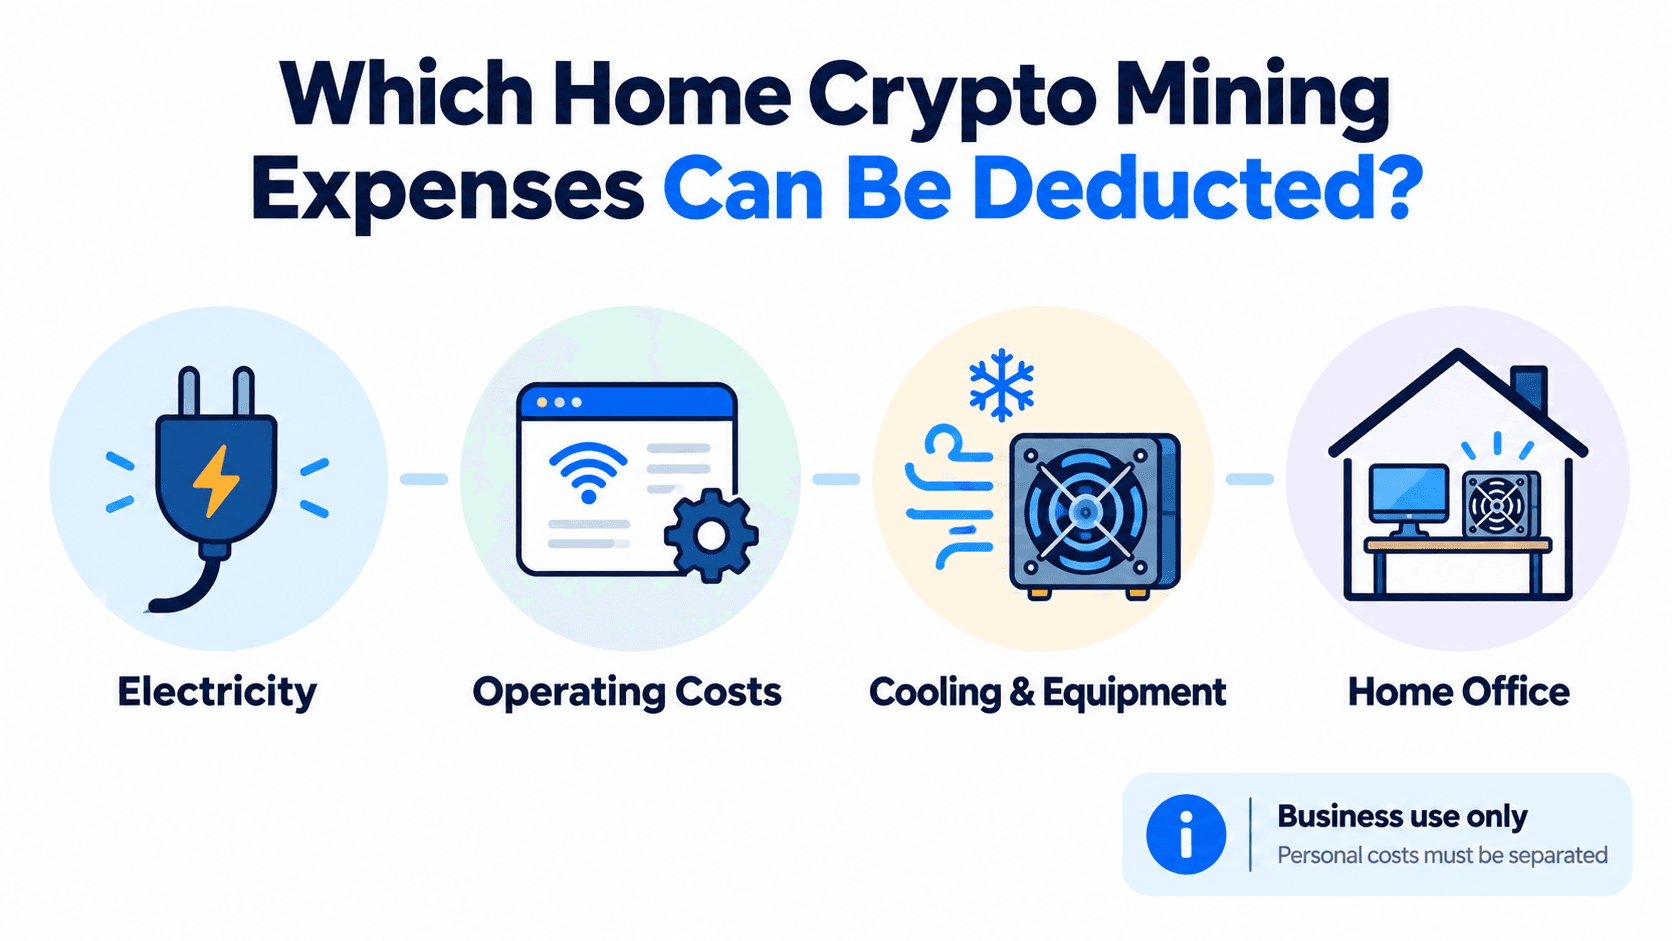
Mining deductions generally depend on the activity qualifying as a trade or business. A business miner may be able to deduct ordinary and necessary operating costs; a hobby miner should not copy the same Schedule C expense list.
Electricity often becomes the largest recurring cost in a home mining operation, so the calculation needs to separate mining consumption from ordinary household use.
 Business Miners Can Deduct Certain Operating Expenses Costs
Electricity
A useful starting calculation is:
ASIC power draw × operating hours = electricity consumption
Suppose an ASIC draws 3.5 kW and runs continuously for 30 days:
3.5 kW × 24 hours × 30 days = 2,520 kWh
At an all-in electricity cost of $0.14 per kWh, the machine consumes roughly $352.80 of electricity for the month.
That calculation alone does not establish a $352.80 deduction. The records should connect the machine's estimated or measured consumption to the actual utility bill and the business use of the equipment.
A home miner may need to account for:
- Shared household meters: Separate mining consumption from ordinary household electricity rather than deducting the full utility bill.
- Dedicated submeters: These can provide cleaner evidence of mining-specific power use.
- Smart-meter data: Hourly usage records may help reconcile operating schedules.
- Time-of-use pricing: A machine running overnight may face a different rate from one running during peak hours.
- Delivery charges and tariffs: The real cost per kWh can include more than the advertised generation rate.
- Cooling: Fans, ventilation or dedicated cooling can create additional mining-specific electricity use.
IRS business-expense rules require mixed personal and business costs to be separated. Utilities used partly for personal purposes do not become fully deductible because mining equipment shares the same meter.
Internet, Pool Fees and Operating Costs
Other ordinary and necessary expenses may include:
- Mining-pool fees
- The business portion of internet service
- Mining or monitoring software
- Bookkeeping
- Tax preparation related to the business
- Maintenance
- Replacement components
- Business subscriptions
Allocation applies whenever an expense serves both household and business use. A shared internet connection, for example, requires a supportable business-use allocation rather than a 100% deduction.
The same principle applies to professional fees. IRS guidance allows the business-related portion of accounting and tax-preparation costs to be deducted on Schedule C when the costs are ordinary and necessary to the business.
Cooling and Electrical Infrastructure
Home mining can generate enough heat and electrical load to require equipment beyond the miner itself.
Possible costs include:
- Exhaust fans
- Ventilation equipment
- Dedicated electrical circuits
- Professional electrical work
- Networking equipment
- Cooling equipment
Tax treatment depends on what was purchased and how it changes the property. A routine repair or replaceable operating component may be treated differently from an improvement that materially upgrades or adapts property for a new use.
IRS business-expense guidance separates current repairs and maintenance from property improvements that generally need to be capitalized.
Solar panels and battery systems can involve property improvements, energy credits, personal use and business allocation at the same time. That combination usually requires a separate tax analysis rather than treating the system as another electricity expense.
Can You Deduct Part of Your Home?
A mining business may sometimes qualify for a business-use-of-home deduction, but placing an ASIC somewhere inside a house does not by itself satisfy the rules.
IRS rules generally require the relevant space to be used regularly and exclusively for the trade or business, subject to specific exceptions. A separately identifiable area can qualify without permanent walls, while personal use can defeat the exclusive-use requirement.
A dedicated room containing mining equipment and business supplies therefore produces a cleaner fact pattern than a basement that also contains family storage, a gaming setup and household tools.
A detached garage or workshop can have different qualification mechanics from a room inside the home. Either way, the miner needs records showing how the area is used rather than estimating a percentage only when preparing the return.
How Are ASICs and Other Mining Hardware Deducted?
Buying an ASIC for a mining business does not automatically produce a full current-year write-off. Mining hardware is generally business property, and its treatment depends on depreciation rules, elections, business use and when the equipment is placed in service.
Three mechanisms usually enter the discussion: Section 179, bonus depreciation and MACRS.
Buying Hardware Does Not Always Mean an Automatic Full Deduction
An ASIC miner, GPU rig or other business mining equipment can be depreciable property. The starting point is generally its business basis and the date it is placed in service, meaning it is ready and available for its intended business use.
Buying a machine in December and leaving it unopened until January can therefore produce a different tax year for depreciation from installing and operating it immediately.
Section 179 vs. Bonus Depreciation vs. MACRS
| Method | Basic Idea | Main Limitation to Understand |
|---|---|---|
| Section 179 | Elect to expense some or all qualifying business property immediately | Subject to eligibility, business-use, dollar and taxable-income limitations |
| Bonus depreciation | Additional first-year depreciation for qualifying property | Property must satisfy the bonus-depreciation rules |
| MACRS | Recover the cost through depreciation over the applicable recovery period | Deduction follows depreciation rules rather than treating the purchase as an ordinary expense |
Section 179 can allow qualifying business property to be expensed in the year it is placed in service. Mixed-use property generally needs more than 50% business use to qualify for the election, and other limits apply.
For qualifying property acquired after Jan. 19, 2025, the One Big Beautiful Bill Act restored a permanent 100% additional first-year depreciation deduction, subject to the applicable rules.
MACRS remains the broader depreciation system used to recover the cost of most depreciable business property over its applicable recovery period. An accountant may therefore discuss expensing a rig under Section 179, claiming bonus depreciation or depreciating remaining basis under MACRS. Each mechanism follows a different set of rules.
Used Hardware, Repairs and Upgrades
Used ASICs can still be depreciable business property when the relevant requirements are met. Keep the purchase invoice, acquisition date, cost and business-use records even when the machine came from a secondary market.
Later spending needs its own classification.
Replacing a failed fan or power-supply unit may look more like repair and maintenance. Replacing hashboards, materially upgrading a machine or rebuilding part of the electrical installation may require capitalization depending on what the work changed.
Keep receipts for small replacement parts as well as major upgrades. Equipment basis becomes difficult to reconstruct once several machines have been repaired, cannibalized for parts, upgraded or sold.
What Happens When You Sell Mining Hardware?
When mining hardware is sold, the business generally compares the sale proceeds with the equipment's adjusted tax basis.
Prior depreciation deductions reduce that basis. If the equipment is sold for more than its adjusted basis, some of the gain may be treated as depreciation recapture rather than receiving the same treatment as an ordinary capital gain.
IRS depreciation guidance directs taxpayers disposing of Section 179 or depreciated business property to the applicable recapture rules for Section 1245 property.
The original invoice, depreciation schedule, repair history and sale record therefore remain connected throughout the machine's tax life.
What Records Should Home Crypto Miners Keep?
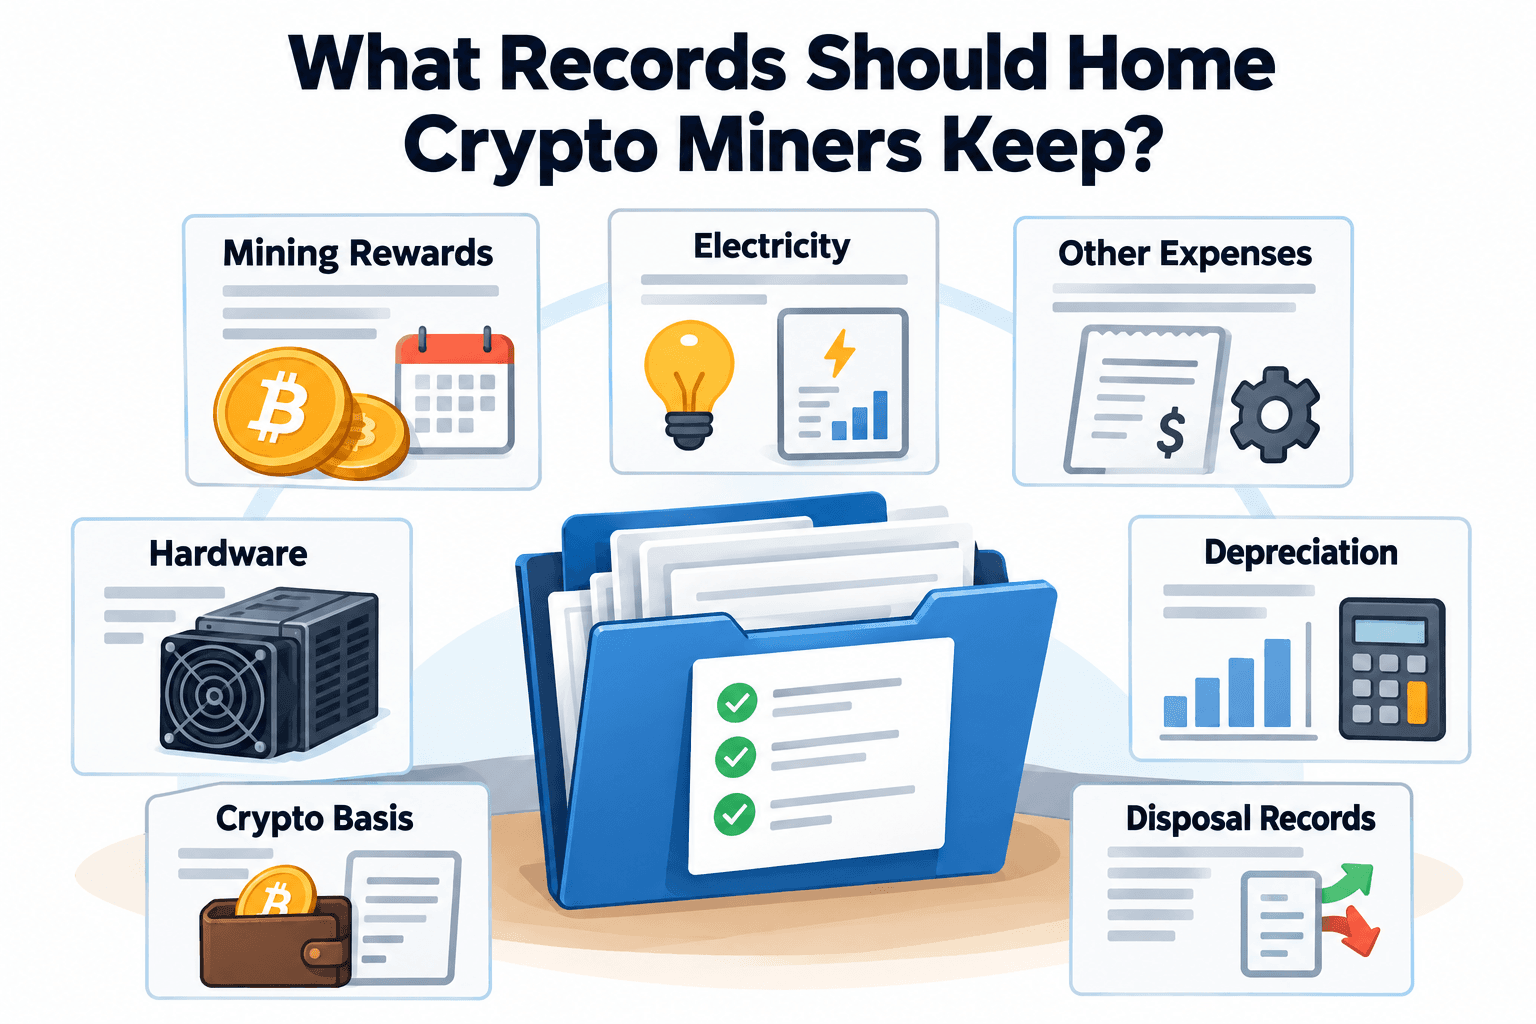
Mining records should let a third party reconstruct three things: how much crypto was received, what the operation cost and what later happened to both the coins and the equipment.
A workable record set looks like this:
| Record Category | What to Preserve |
|---|---|
| Mining rewards | Date, time, asset, quantity, USD value, valuation source, pool, wallet, TXID |
| Electricity | Utility bills, kWh calculations, meter readings, tariff data, allocation method |
| Other expenses | Receipts, invoices, pool fees, software, repairs, professional fees |
| Hardware | Purchase cost, sales tax, shipping, acquisition date, placed-in-service date |
| Depreciation | Business-use percentage, method, elections, prior deductions, adjusted basis |
| Disposal records | Sale date, proceeds, buyer/platform record, hardware basis |
| Crypto basis | Income value at acquisition, wallet location, lot identification, later disposition |
IRS digital-asset guidance requires taxpayers to maintain enough documentation to support reported transactions, including receipts, sales, exchanges, dispositions, transfers and fair market values.
 Strong Mining Records Support Income, Expenses And Basis
Mining Reward Records
For every taxable mining reward, preserve:
- Date and time
- Asset
- Quantity
- USD fair market value
- Valuation source
- Mining pool
- Receiving wallet
- Transaction ID, where applicable
An onchain record can confirm that a blockchain transaction occurred, but it may not show the pool account, valuation methodology, business purpose or tax classification.
Likewise, a wallet address identifies where crypto moved. It does not by itself establish who controlled the address, whether the movement was taxable or what basis belonged to the assets.
Electricity and Expense Records
Keep:
- Utility bills
- kWh calculations
- Meter or submeter readings
- Electricity tariff information
- Time-of-use data where relevant
- Business-versus-personal allocation methodology
- Receipts and invoices
If the allocation method changes during the year, keep the reason for the change. Installing a submeter or gaining access to more detailed smart-meter data may justify a different methodology from the one used earlier.
Hardware Records
For each rig or major piece of equipment, retain:
- Purchase price
- Sales tax
- Shipping
- Acquisition date
- Placed-in-service date
- Business-use percentage
- Depreciation records
- Repair and upgrade records
- Sale or disposal details
A hardware register becomes particularly useful once rigs are moved, upgraded, partially dismantled or sold.
Track Cost Basis After Mining
The amount recognized as income generally becomes the starting basis of the mined crypto. From that point, the miner needs to know which units sit in which wallet and which units are later disposed of.
Track:
- Acquisition lots
- Transfers between wallets
- Wallet ownership
- Disposal records
- Holding periods
- Basis assigned to units sold
Transfers between wallets or accounts owned by the same taxpayer are generally non-taxable transfers. Using crypto to pay a network fee can create a separate disposition of the crypto used for that fee.
Moving mined coins into self-custody changes who controls transaction authorization; it does not by itself turn the transfer into a sale. If the coins are stored on a hardware wallet, the taxpayer still needs the original acquisition and basis records because the device does not reconstruct the tax history.
Control over private keys proves the ability to authorize blockchain transactions, but it does not establish the fair market value originally reported as mining income. A seed phrase can restore wallet access, but it cannot restore missing tax records.
Since Jan. 1, 2025, digital-asset basis identification has increasingly operated through a wallet-by-wallet or account-by-account framework. Revenue Procedure 2024-28 provided transitional rules for unused basis associated with earlier holdings, making wallet-level acquisition records more useful for later disposals.
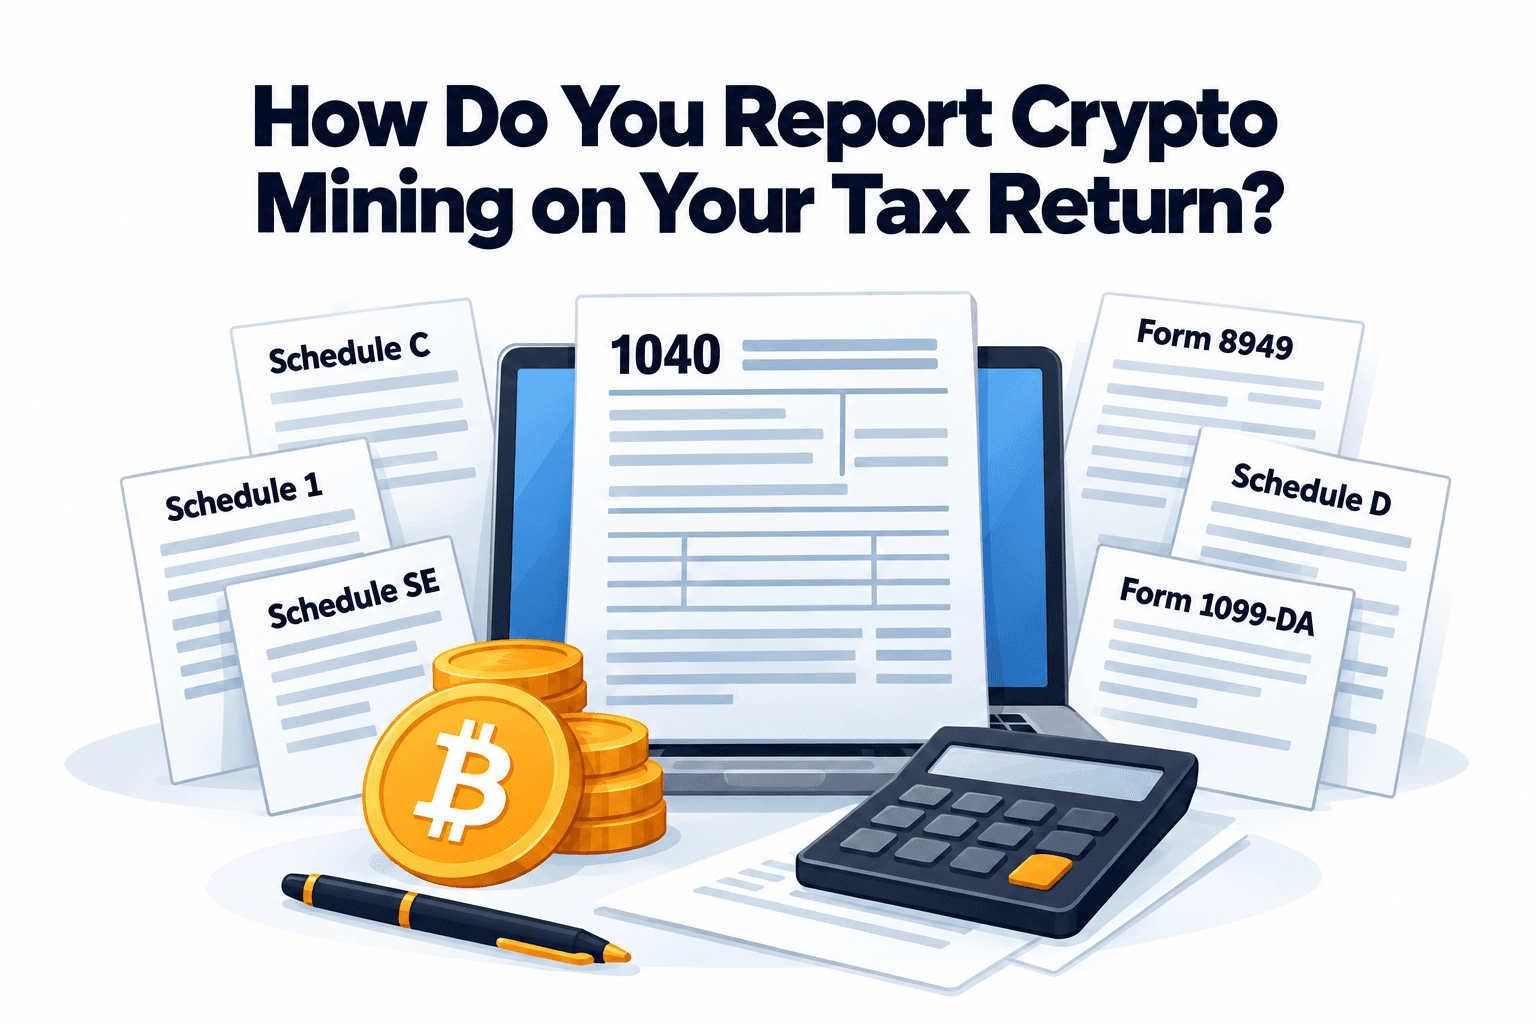
How Do You Report Crypto Mining on Your Tax Return?
Mining income, business profit and later crypto sales can land on different forms. The reporting route follows the character of each transaction.
| Form / Schedule | Typical Mining-Tax Role |
|---|---|
| Form 1040 / Schedule 1 | Nonbusiness or hobby mining income |
| Schedule C | Mining-business income and deductible business expenses |
| Schedule SE | Self-employment tax where applicable |
| Form 8949 | Individual digital-asset sale and exchange reporting where required |
| Schedule D | Aggregated capital gains and losses |
| Form 1099-DA | Broker-reported digital-asset dispositions |
| Form 1099-NEC / 1099-MISC | Certain payment relationships that may generate information reporting |
Reporting Hobby Mining Income
Hobby status does not make mining rewards tax-free. Nonbusiness ordinary digital-asset income is generally reported through Form 1040 and Schedule 1 rather than Schedule C.
The IRS's digital-asset reporting guidance identifies mining among the types of ordinary digital-asset income that may be reported through Schedule 1.
The business deductions discussed earlier should not be imported into a hobby return. Classification determines which expense rules apply.
 Mining Tax Reporting Spans Several Different IRS Forms
Reporting Mining as a Business
A sole proprietor conducting mining as a trade or business generally reports business income and allowable expenses on Schedule C. The resulting net profit or loss then feeds into the individual return.
If net earnings from self-employment reach the applicable threshold, Schedule SE calculates self-employment tax.
The headline self-employment tax rate in 2026 is 15.3%, comprising 12.4% Social Security and 2.9% Medicare. The actual calculation uses net earnings rather than gross mining revenue, the Social Security portion is subject to the applicable wage base, and Additional Medicare Tax can apply at higher income levels.
A miner with $20,000 of rewards and $12,000 of deductible business expenses therefore has a different self-employment calculation from someone with $20,000 of rewards and almost no deductible costs.
Reporting the Sale of Mined Crypto
When mined crypto held as a capital asset is later sold, swapped or otherwise disposed of, the taxpayer generally calculates:
Proceeds − adjusted basis = capital gain or loss
Reporting may involve Form 8949 and Schedule D, including:
- Proceeds
- Cost basis
- Acquisition date
- Disposal date
- Short-term or long-term treatment
- Adjustments where required
Form 8949 is used to reconcile capital-asset transactions, including transactions reported through Form 1099-DA, before gains and losses flow into Schedule D.
The acquisition record created when the mining reward was recognized provides the basis needed for that later calculation.
Form 1099-DA, 1099-NEC and No Tax Form
Form 1099-DA is primarily a broker-disposition form. It is not a universal mining-reward form.
| Document | What It Usually Tells You |
|---|---|
| 1099-DA | A broker reported a digital-asset sale or other covered disposition |
| 1099-NEC / 1099-MISC | A payer may be reporting qualifying compensation or another payment |
| No form | The taxpayer may still have taxable mining income or reportable gains |
IRS instructions describe Form 1099-DA as the form brokers use to report digital-asset sales, with basis reporting applying to certain covered digital assets under the phased-in broker-reporting regime.
A 1099-NEC or 1099-MISC can arise in some payment arrangements. The form reports information; it does not decide whether the underlying income is taxable.
For payments made in 2026, the One Big Beautiful Bill Act raised the statutory information-reporting threshold for certain payments covered by Sections 6041 and 6041A from $600 to $2,000. That change affects information-reporting obligations. It does not create $2,000 of tax-free mining income.
Taxable digital-asset income, gains and losses can still require reporting when no information form is issued.
Do Home Miners Need Quarterly Estimated Tax Payments?
They may.
Mining-business income usually arrives without employer withholding. Taxpayers expecting to owe enough federal tax may therefore need to make estimated payments during the year.
For 2027, an individual generally enters estimated-tax territory when they expect to owe at least $1,000 after withholding and refundable credits and their withholding and credits fall below the applicable safe-harbor levels.
Someone who also earns W-2 wages may increase payroll withholding to cover some or all of the additional tax instead of relying exclusively on separate quarterly payments.
The calculation depends on the taxpayer's entire return, including wages, mining profit, other income, deductions, credits and withholding.
Home Crypto Mining Tax Examples
The examples below put income recognition, deductions and later asset disposal into the same timeline.
They simplify the numbers to show the tax mechanics rather than calculate a complete federal return.
Example 1: Casual Home Miner
Maria runs a small miner occasionally and receives $900 of crypto during the year based on its fair market value when received.
Her activity is treated as a hobby.
She generally has:
- $900 of mining income to report
- No Schedule C business treatment for the mining activity
- No ordinary business deduction simply for the electricity or hardware
- A starting tax basis in the mined crypto tied to the amount included in income
Suppose she later sells the crypto for $1,100. The original mining income remains $900. The later sale potentially creates a $200 capital gain.
Example 2: Home Mining Business
David operates several ASICs continuously and runs the activity as a genuine business.
During the year, assume he records:
- $30,000 of mining rewards at fair market value when taxable
- $11,000 of properly substantiated mining electricity
- $1,200 of pool fees
- $800 of other deductible operating costs
He also purchased qualifying mining hardware used in the business. Its tax treatment may involve Section 179, bonus depreciation or MACRS depending on the facts and elections made.
The $30,000 of mining rewards forms gross business income. Legitimate business expenses reduce Schedule C profit. The resulting net earnings can then affect self-employment tax.
Each mined lot also receives a tax basis tied to the amount included in income. Selling those coins later creates separate gain-or-loss calculations.
Mining revenue therefore tells the miner how much value was earned. Schedule C profit reflects what remains after allowable business expenses.
Example 3: Bitcoin Drops After It Is Mined
Suppose a miner receives BTC worth $10,000 when the reward becomes taxable.
The miner reports $10,000 of income.
Bitcoin then falls before the miner sells.
By the time the BTC is disposed of, it is worth only $6,000.
The original $10,000 income remains tied to the value of the reward when it was received. Assuming a $10,000 basis and no other adjustment, the later sale potentially creates a $4,000 capital loss.
The cash problem is straightforward: the miner can owe tax on $10,000 of mining income while eventually receiving only $6,000 from selling the asset. Holding every reward until year-end can therefore leave a miner short of cash even when the eventual crypto position loses money.
Common Crypto Mining Tax Mistakes
Most home-mining errors come from mixing income rules, business deductions and crypto basis into one calculation.
Common mistakes include:
- Treating the $400 self-employment threshold as tax-free mining income.
- Claiming Schedule C-style mining deductions while treating the activity as a hobby.
- Deducting the entire household electricity bill instead of substantiating mining use.
- Failing to record the U.S. dollar value of rewards when they become taxable.
- Ignoring pool records because rewards eventually went directly to a private wallet.
- Forgetting that selling, swapping or spending mined coins can create a later taxable disposal.
- Treating transfers between personally owned wallets as sales.
- Assuming no Form 1099 means no reporting obligation.
- Confusing Form 1099-DA with a universal mining-reward form.
- Losing ASIC invoices, placed-in-service dates and depreciation records.
The IRS sees tax events through income, ownership and disposal. Moving assets between addresses, changing custody methods or receiving no tax form does not by itself rewrite those events.
Home Crypto Mining Tax Checklist
A workable mining-tax process starts while the equipment is running, before the records have to be reconstructed for Form 1040.
- Determine whether the activity is likely a hobby or trade or business.
- Export mining-pool records and wallet histories.
- Calculate the U.S. dollar fair market value of mining rewards using a consistent methodology.
- Record the resulting tax basis for each mined lot.
- Separate personal electricity from substantiated mining consumption.
- Preserve ASIC, GPU and other hardware invoices and placed-in-service dates.
- Categorize legitimate business expenses separately from personal spending.
- Reconcile later sales, swaps or spending of mined crypto against the original basis records.
- Check Forms 1099-DA, 1099-NEC, 1099-MISC or other information returns against your own records rather than assuming they are complete.
- Determine whether estimated payments or additional W-2 withholding are appropriate.
- Preserve the source records behind any summarized tax-software reports.
- Use a qualified tax professional when hobby-versus-business status, depreciation, missing historical basis or prior-year reporting is unclear.
Closing Thoughts
Home crypto mining can create a tax obligation before a miner sells a single coin. The fair market value of a reward when the miner gains control generally becomes taxable income and establishes the asset’s starting cost basis. If that crypto is later sold, swapped or spent, the change in value from that basis can produce a separate capital gain or loss.
How the mining activity is run then shapes much of what follows. A hobby miner and a business miner may receive the same type of reward, but business classification can bring Schedule C expenses, self-employment tax and depreciation into play. Electricity, pool fees, cooling costs and mining hardware can all affect the economics of a genuine mining business, although each deduction needs records that separate business use from personal use. ASICs and other equipment also have their own tax lifecycle, from purchase and depreciation through repairs and eventual disposal.
For a home miner, the practical job is to keep those pieces connected. Pool records establish what was earned, valuation records support the income figure, expense and hardware documents support business deductions, and wallet-level records preserve basis for future disposals. Forms such as Schedule C, Schedule SE, Form 8949 and Schedule D then report different parts of that history. Keeping those records as mining happens turns filing into reconciliation rather than an attempt to reconstruct a year of rewards, electricity bills and wallet movements after the fact.